CBO 100
At the end of the Cash Back Option period, you may request to terminate and receive 100% of base premiums paid (less any outstanding loans), if the benefit is still in effect.
Mortgage protection · Cash Back Option
Mortgage-focused coverage that helps your family pay the loan if you pass away. With a Cash Back Option, you may reclaim 50% or 100% of base premiums at the end of the period if you never need the claim.
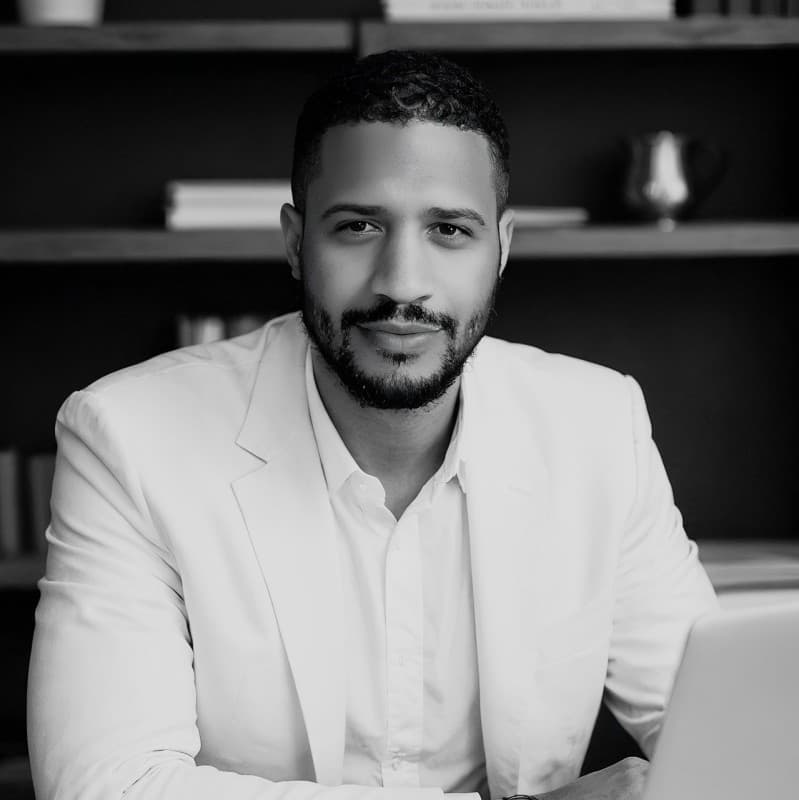 Paul GipsonLicensed life insurance producer · NPN 21670586 · Los Angeles, CA
Takes about 60 seconds. I'll personally review it and reach out.
Cash Back Option
Hopefully you outlive your mortgage in good health. CBO products are built so you have life insurance while you need it—and a contractual path to get base premiums returned if you terminate at the end of the cash-back period.
At the end of the Cash Back Option period, you may request to terminate and receive 100% of base premiums paid (less any outstanding loans), if the benefit is still in effect.
Same idea at a lower premium: at the end of the period you may reclaim 50% of base premiums paid (less loans) when you request the cash-back surrender in time.
Common cash-back / level periods include 15, 20, 25, and 30 years—so you can align protection with how long you’ll be paying the mortgage.
Many applicants answer a few health questions with no medical exam. You’ll often know if you’re covered quickly after applying.
Cash-back amounts apply to base policy premiums only—not rider premiums. Surrender must be requested within the product’s window after the anniversary (often 60 days). Loans reduce the amount returned. Examples are illustrative; your illustration will show exact numbers.
Living benefits
Living Benefit riders can give you access to an early (accelerated) payout of death benefits if you’re diagnosed with a qualifying illness. On qualifying products these living benefits are included at no additional premium—and that money can help with treatment, bills, or keeping the household running.
A lump-sum acceleration if you’re diagnosed with a qualifying critical illness such as invasive cancer, stroke, or heart attack.
Help if a catastrophic health crisis leaves you unable to perform two activities of daily living for a qualifying period—funds that can go toward care and other expenses.
A lump-sum benefit if you’re diagnosed with a qualifying terminal illness (typically life expectancy of 12 months or less)—usable for any purpose.
Accelerations are subject to eligibility, policy terms, administrative charges, and actuarial discounts. Requested amounts may result in little or no payment. Living benefits reduce the remaining death benefit. Not all benefits are available on every product or in every state.
HOW IT WORKS
No fees, no obligation, and you can stop at any step.
STEP 1
60 seconds: who you're protecting, your budget, and the best way to reach you.
STEP 2
I run your numbers across 15+ carriers and call within 1 business hour—or pick a time on my calendar that suits you.
STEP 3
We pick the plan together and I handle the application and follow-ups until your policy is in force.
MEET PAUL
I'm Paul Gipson, a licensed life insurance producer (NPN 21670586) serving families in 10 states. LifeAgentPaul isn't a brand with a sales floor behind it—it's me.
My name is on the line every time I recommend a plan. I'll show you term, whole life, IUL, and final expense options side by side, tell you which one I'd pick for your situation and why, and then stay available as your needs evolve.
I'm Paul Gipson. I built LifeAgentPaul to make life insurance feel approachable—I combine licensed expertise with clear education so you understand premiums, death benefits, riders, and exclusions before you sign. Below are the actual state licenses I hold, so you can verify them yourself.
Whether you're covering a mortgage, protecting your income, or building a legacy for your family, you get a roadmap from me—not a sales pitch.
I'm licensed for life insurance in the 10 states below. Select a state with an underline to view the credential image.
“I'll help you stay protected when life changes—and I'll answer when you call. Your family's future is a relationship to me, not a one-time sale.”
Looking at other coverage too?
Ready when you are
Fill this out and I'll personally reach out within 1 business hour—no call center, just me.